• Economy
  • Editor’s Pick
Money Rise Today – Investing and Stock News
  • Investing
  • Stock
Investing

DCF model suggests Cerebras stock is still overvalued

by October 12, 2026
written by October 12, 2026

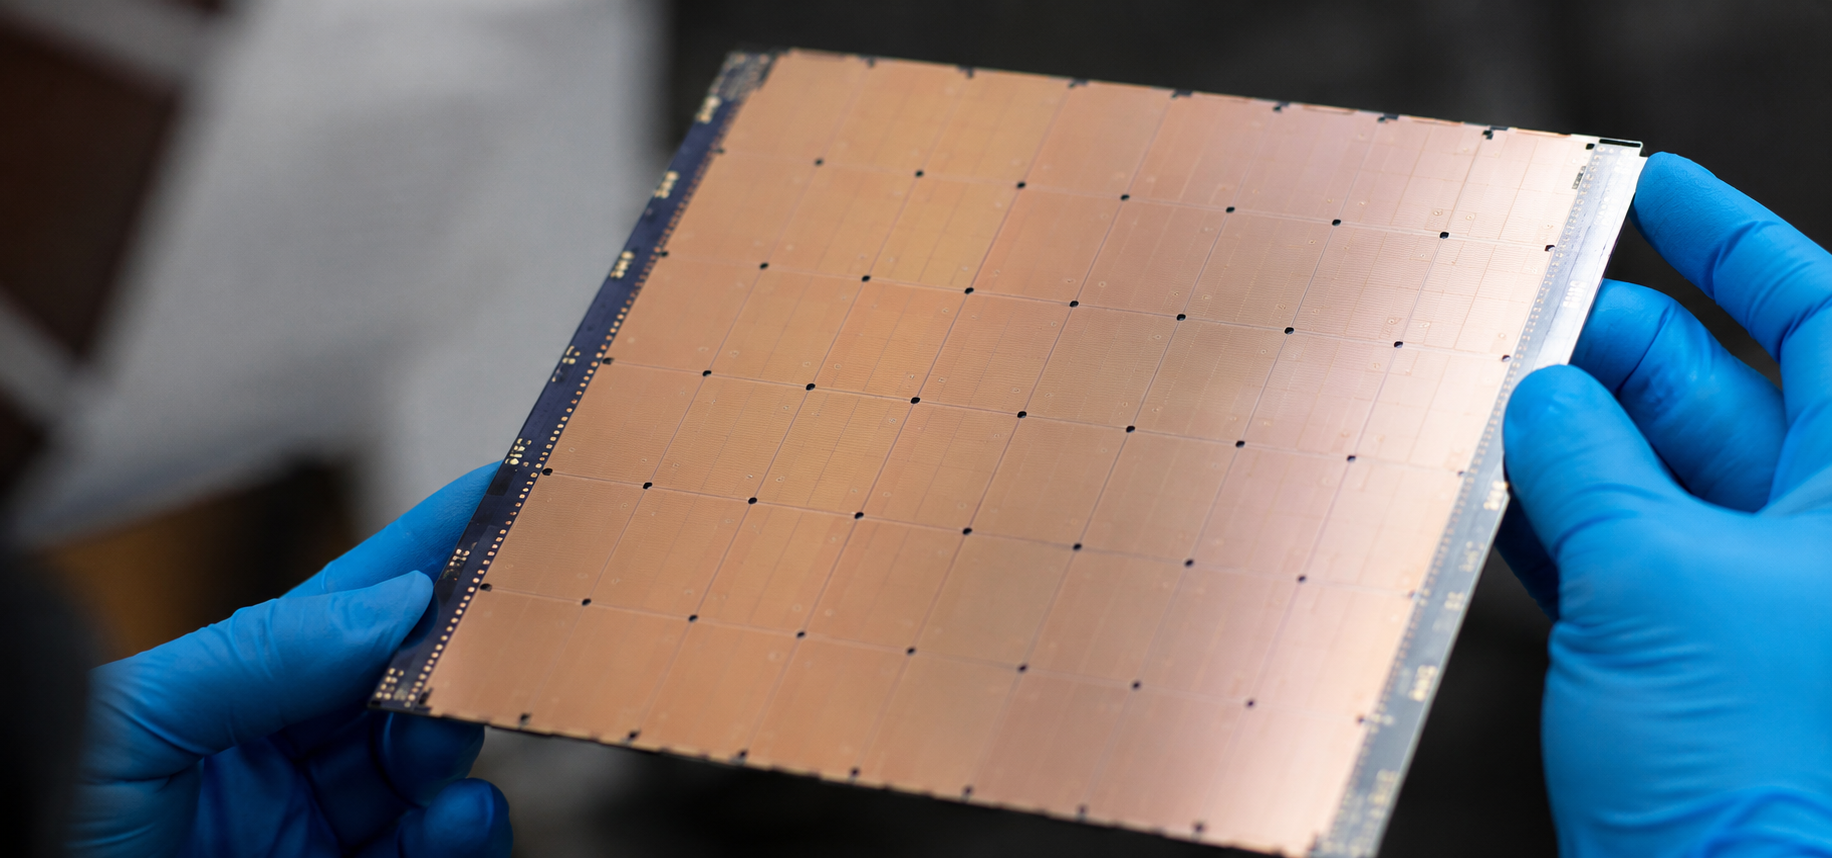
Cerebras Systems (CBRS) shares are extending losses on October 12th as investors continue to reassess the artificial intelligence (AI) infrastructure company’s future prospects.

CBRS is now trading at about half its price at the start of 2026, yet an illustrative discounted cash flow (DCF) analysis suggests it’s still overvalued for risk-averse investors.

For those interested in buying the dip in Cerebras stock, the central question is whether rapid sales expansion can ultimately translate into durable cash generation.

Our assumptions for the DCF model

Cerebras Systems’ latest outlook targets $880 million – $890 million in 2026 core revenue, while management plans to more than triple revenue in 2027.

Its $25.4 billion in remaining performance obligations (RPOs) provides substantial visibility into contracted business, although those commitments are not equivalent to immediate cash flow.

DCF’s base case assumes “economic revenue” reaches $2.8 billion next year, $10.5 billion in 2031, and $19.2 billion by 2036.

It also assumes free cash flow (FCF) margin improves from negative 25% to positive 22% over that period.

While these assumptions aren’t official company forecasts, they’re still ambitious given Cerebras must absorb considerable investment needed to expand computing capacity before delivering cash to shareholders.

Why CBRS shares are not undervalued yet

Discounting projected cash flows at 12% – with perpetual growth of 3% after 2036 – produces an estimated enterprise value of $21.2 billion.

Adding $6.2 billion in assumed adjusted net cash brings equity value to roughly $27.4 billion, and dividing that figure by an assumed 285 million diluted shares yields $96 fair value for CBRS stock.

The cash adjustment allows for spending after June, while the share count incorporates an allowance for warrants and employee equity. Neither represents a reported October balance-sheet figure.

Alternative scenarios demonstrate the uncertainty: weaker growth and profitability produce a value near $34 – while exceptional growth and a 30% terminal FCF margin support about $258 per share.

Cerebras Systems still requires exceptional execution

The DCF model suggests Cerebras shares look expensive under base assumptions, despite the selloff.

Holding margins, dilution, and discount rates constant, justifying $150.85 would require a revenue trajectory about 74% above the base case – reaching roughly$33 billion in 2036, alongside $7.3 billion in annual free cash flow.

Stronger margins or lower investment requirements could also support today’s valuation. However, about 72% of base-case enterprise value comes from the terminal value – making the result highly sensitive to distant expectations.

Investors should therefore treat $96 as a scenario estimate, rather than a precise price target.

In short, Cerebras Systems’ opportunity remains rather huge – but the company’s current price still demands considerable long-term success.

That said, Wall Street rates it at Buy currently, with a bullish mean price target of about $291.

The post DCF model suggests Cerebras stock is still overvalued appeared first on Invezz

0 comment
0
FacebookTwitterPinterestEmail

previous post
Strategy stock (MSTR) slips as Bitcoin purchase hits yearly low of 250 BTC
next post
Northland analyst says it’s time to hop back into C3.ai stock

related articles

The complicated business of betting on Big Tech’s...

November 21, 2026

FT finds Alice Huang linked to chip network...

November 21, 2026

Is Nvidia’s Colette Kress standing on a glass...

November 21, 2026

Will Jensen Huang’s ouster push founders to secure...

November 21, 2026

Michael Burry takes profits on Nvidia puts as...

November 20, 2026

Why Intel shares are falling over 5% on...

November 20, 2026

PayPal stock falls 4% as leadership shake-up tests...

November 20, 2026

Evening digest: Anthropic slides after record debut, Bitcoin...

November 20, 2026

Why Broadcom shares are down over 11% on...

November 20, 2026

Why CoreWeave and Nebius stocks are falling on...

November 20, 2026
Enter Your Information Below To Receive Free Trading Ideas, Latest News, And Articles.


Your information is secure and your privacy is protected. By opting in you agree to receive emails from us. Remember that you can opt-out any time, we hate spam too!

Latest News

  • SpaceX rally sparks tech-stock bubble concerns, fuels meme-stock comparisons

    June 17, 2026
  • FIRST ON FOX: DHS points to ‘common sense’ reason for collapsing crime: ‘No surprise’

    August 1, 2026
  • Barclays says oil and rates, not midterms, will decide equities this fall

    September 23, 2026
  • Dow futures surge 370 points: 5 things to know before market opens

    June 11, 2026
  • Bank of England warns AI could amplify market and cyber risks

    July 7, 2026

Popular Posts

  • 1

    Why SpaceX stock is down around 3% on Tuesday

    September 15, 2026
  • 2

    Micron stock falls 4%, why this analyst sees 40% upside for the stock?

    September 28, 2026
  • 3

    Evening digest: US jobs cool, gold falls as Treasury yields rise

    October 2, 2026
  • 4

    Nike stock sinks after earnings as its comeback plan turns into more layoffs

    October 2, 2026
  • 5

    Dow rises 260 points as weak jobs data lifts US stocks

    October 2, 2026

Categories

  • Editor's Pick (711)
  • Investing (2,694)
  • Stock (90)

Latest Posts

  • SoftBank jumped 4% then crashed nearly 6%: what changed in just 24 hours?

    October 2, 2026
  • Why CoreWeave shares are up 2% on Monday?

    October 19, 2026
  • Intel stock faces $13 billion Nvidia dilemma: what happens if Jensen Huang goes?

    November 12, 2026

Recent Posts

  • SpaceX slips after blockbuster IPO rally: is hype catching up with fundamentals?

    June 17, 2026
  • Nvidia stock hits key support, forms bullish pattern as key valuation metric dips

    July 8, 2026
  • Why this analyst sees a 30% upside for Meta stock?

    November 17, 2026

Editor’s Pick

  • It’s not just SpaceX: These top Scottish Mortgage Trust stocks are in trouble

    June 24, 2026
  • Amazon plans $7 billion acquisition of Decart, a fast-growing AI startup

    October 11, 2026
  • Top FTSE 100 shares to watch next week: IAG, BT Group, National Grid, Diageo

    October 30, 2026
  • About us
  • Contacts
  • Privacy Policy
  • Terms & Conditions

Disclaimer: moneyrisetoday.com, its managers, its employees, and assigns (collectively “The Company”) do not make any guarantee or warranty about what is advertised above. Information provided by this website is for research purposes only and should not be considered as personalized financial advice. The Company is not affiliated with, nor does it receive compensation from, any specific security. The Company is not registered or licensed by any governing body in any jurisdiction to give investing advice or provide investment recommendation. Any investments recommended here should be taken into consideration only after consulting with your investment advisor and after reviewing the prospectus or financial statements of the company.

Copyright © 2025 moneyrisetoday.com | All Rights Reserved

Money Rise Today – Investing and Stock News
  • Economy
  • Editor’s Pick
Money Rise Today – Investing and Stock News
  • Investing
  • Stock